Skip to content

Search

"merchant risk"

77 articles found

BKM HİYS dispute and chargeback management workflow

Chargeback

What Is HİYS (Dispute Management System)?

The Dispute Management System (HİYS) is the system used among BKM members to share chargeback transactions and the supporting documents that must accompany them, linked to Domestic Clearing and Settlement System data.
Mifare contactless smart card

Debit Card

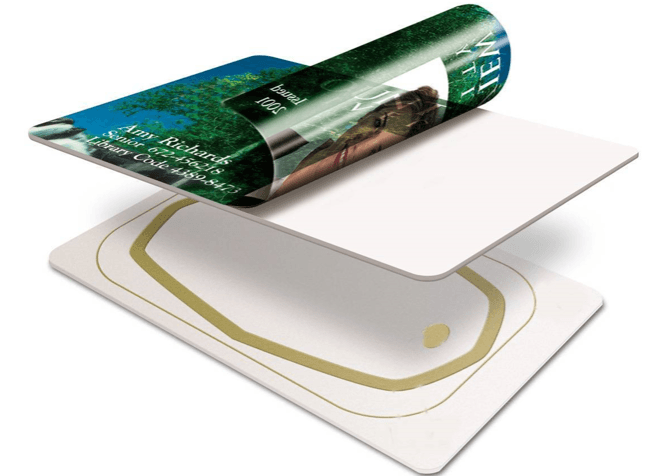
What is a Mifare Card?

A type of smart card containing a microchip and simple software, which performs contactless reading when brought close to a smart card reader. It isn't linked to a bank account and has no credit limit like credit cards. You can spend up to the amount loaded onto the card...

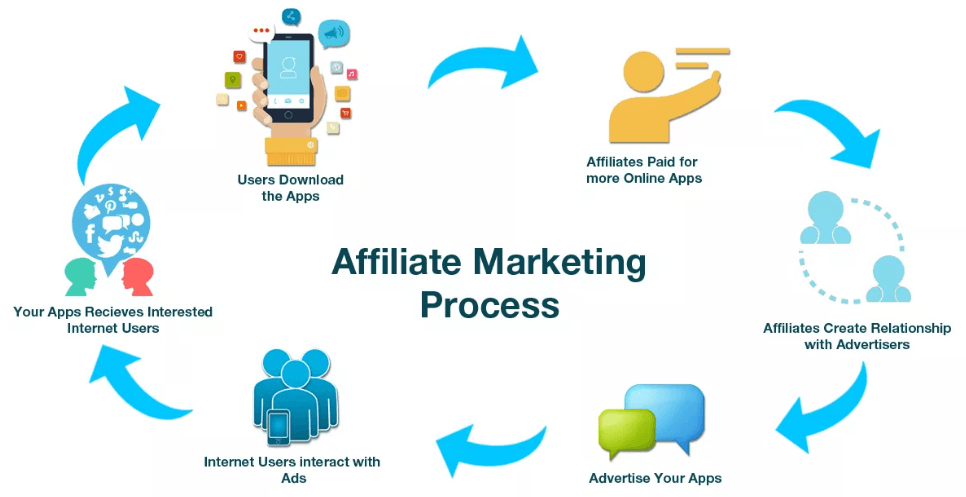
Diagram of the affiliate marketing relationship between merchant, affiliate, and customer

Payment Systems

What is Affiliate Marketing?

Affiliate marketing, in short, is a performance-based promotion and sales approach that distributes an online retailer's product marketing to different people and organizations, letting it achieve the most sales with the least risk.

Illustration explaining OTP one-time password verification

Security

What Is OTP (One-Time Password)?

These are passwords generated for one-time use and sent to the cardholder's phone to verify card transactions in payment systems. The password sent during a 3D Secure transaction is a common example.

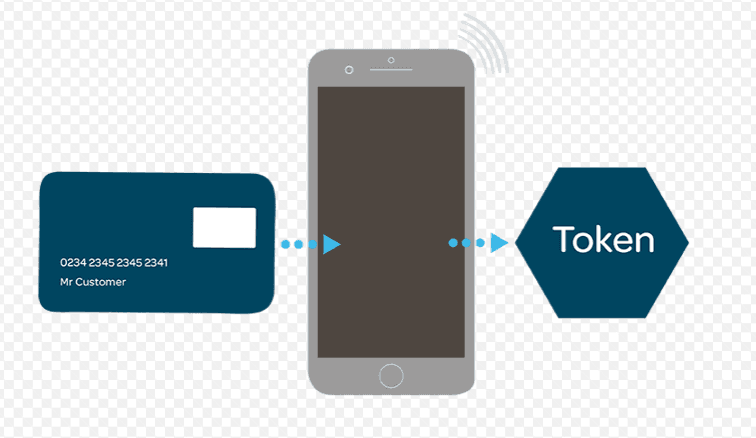
Diagram comparing the three levels of payment-card tokenization: static, semi-dynamic and dynamic

HCE

What Are the Levels of Tokenization?

Generating a token from the card number is essential to the security of payments made with mobile devices. The level of tokenization used depends on the need and on how critical the token is. Static tokenization: the token is generated once and stored in a database.

Diagram of the chargeback process between cardholder, issuer and acquirer

Chargeback

How to Reduce Chargebacks (For Cardholders)

A chargeback is when a cardholder asks the issuing bank to refund a transaction made without their knowledge. It cannot be prevented entirely, but simple precautions can minimize the risk. Here is how the process works and what cardholders should do.

Illustration representing Strong Customer Authentication (SCA) under PSD2

Payment Systems

What is Strong Customer Authentication (SCA)?

Strong Customer Authentication (SCA) is a security requirement introduced under the EU's Payment Services Directive 2 (PSD2) to increase security and reduce fraud in online payment transactions. SCA requires two of three independent authentication factors.