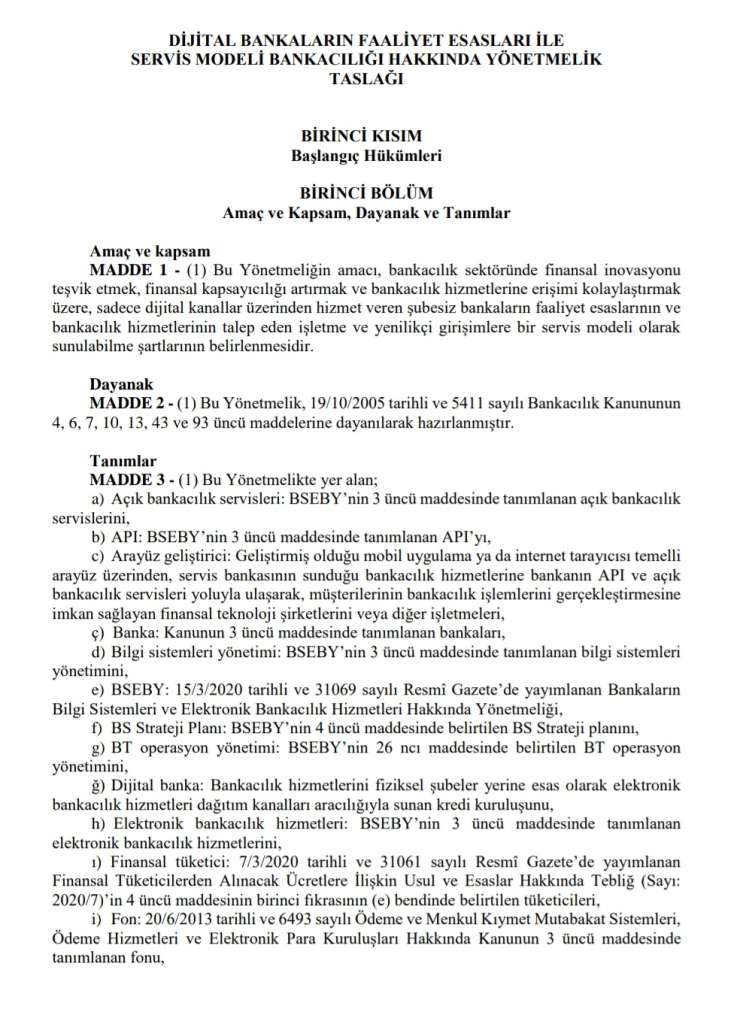
Under the Communiqué, service model banking will not require a BRSA operating license.
It is provided that the services banks will offer to interface developers through service model banking will be considered within the scope of subparagraph 4/1-v of the article titled fields of activity of Banking Law No. 5411, and accordingly banks will not need to apply to the BRSA for an extension of activities in order to offer interface developers the services they can provide within the framework of their existing operating licenses.
However, before signing a contract with the interface developer, the service bank will need to notify the BRSA in writing about the scope of the services it will provide, together with information about the interface developer it plans to serve and showing which banking services it plans to make available.
The details of the communiqué can be accessed from the link below:
https://www.bddk.org.tr/Mevzuat/DokumanGetir/1050
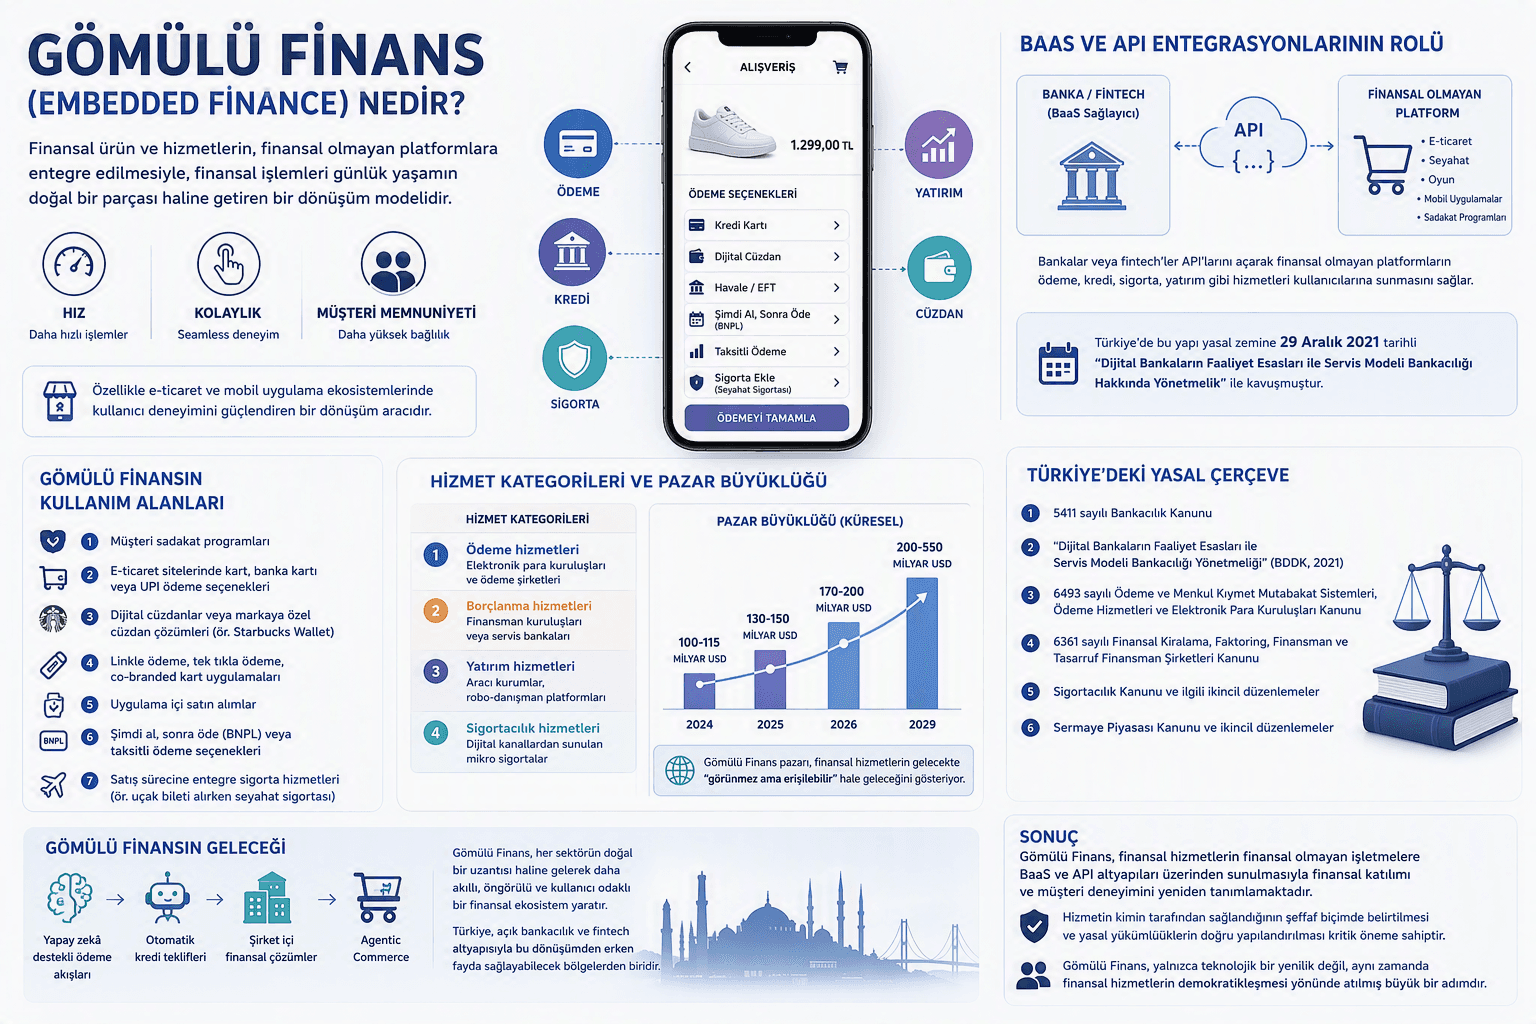
Division of labor between the bank and the fintech
In the service model, the bank offers the banking service through an API, while the interface developer serves the customer on the app side. The bank remains responsible for the regulated activity.
This model helps fintech companies create innovative products without a banking license. On the other hand, the bank expects the interface developer to comply in areas such as security, authentication and customer disclosure.
Fintechs should clearly address data use and the allocation of responsibility in contracts.