Skip to content

Search

"European payments"

20 articles found

European Payments Initiative (EPI) overview graphic

Payment System Institutions

What is EPI (European Payments Initiative)?

The European Payments Initiative (EPI), formerly known as PEPSI, is an ECB-backed payment integration initiative aiming to build a pan-European payment system and interbank network to rival Mastercard and Visa. Its founding members include BBVA, BNP Paribas, CaixaBank, Commerzbank and others.
Diagram illustrating the PSD (Payment Services Directive) regulatory framework

Merchant & POS

What is PSD (Payment Services Directive)?

PSD stands for Payment Services Directive, known as the Payment Services Law. It took effect in EU countries in 2009, and in 2015 new revisions were announced as PSD1, aiming to build an efficient, fast, secure, and competitive payment market.

European Association for Secure Transactions EAST

ATM

What Is the European ATM Security Team (EAST)?

EAST, originally the European ATM Security Team, is a non-profit organization working on ATM security. Founded in 2004, it later broadened its scope and became the European Association for Secure Transactions.

EU Payment Services Directive 2 PSD2

Merchant & POS

What Is the EU Payment Services Directive 2 (PSD2)?

The EU Payment Services Directive 2 (PSD2) is the EU's payment services law. ÖDED translated it into Turkish, creating an important handbook for anyone wanting to invest or work in this area.

Payment Services Directive PSD1 and PSD2 overview

Payment Institutions & E-Money

What Is the Payment Services Directive?

The first Payment Services Directive (PSD1) was adopted in 2007 to provide the legal basis for a single EU payments market. PSD2, Directive 2015/2366, replaced it to make payments safer, more integrated and more competitive.

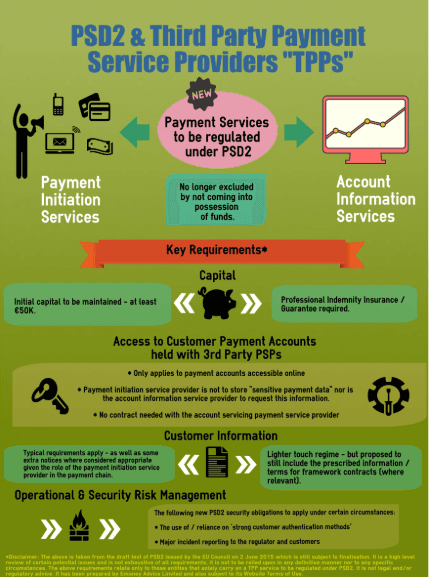
Open banking illustration representing payment services data sharing APIs between financial institutions and third-party providers

Payment Systems

Guide on Data Sharing Services in Payment Services Published

Open banking opens financial data, under the regulations and with the customer's explicit consent, to third-party service providers through standard APIs. The CBRT has published a guide on payment initiation and account information services, covering licensing and technical certification.

Illustration representing Strong Customer Authentication (SCA) under PSD2

Payment Systems

What is Strong Customer Authentication (SCA)?

Strong Customer Authentication (SCA) is a security requirement introduced under the EU's Payment Services Directive 2 (PSD2) to increase security and reduce fraud in online payment transactions. SCA requires two of three independent authentication factors.

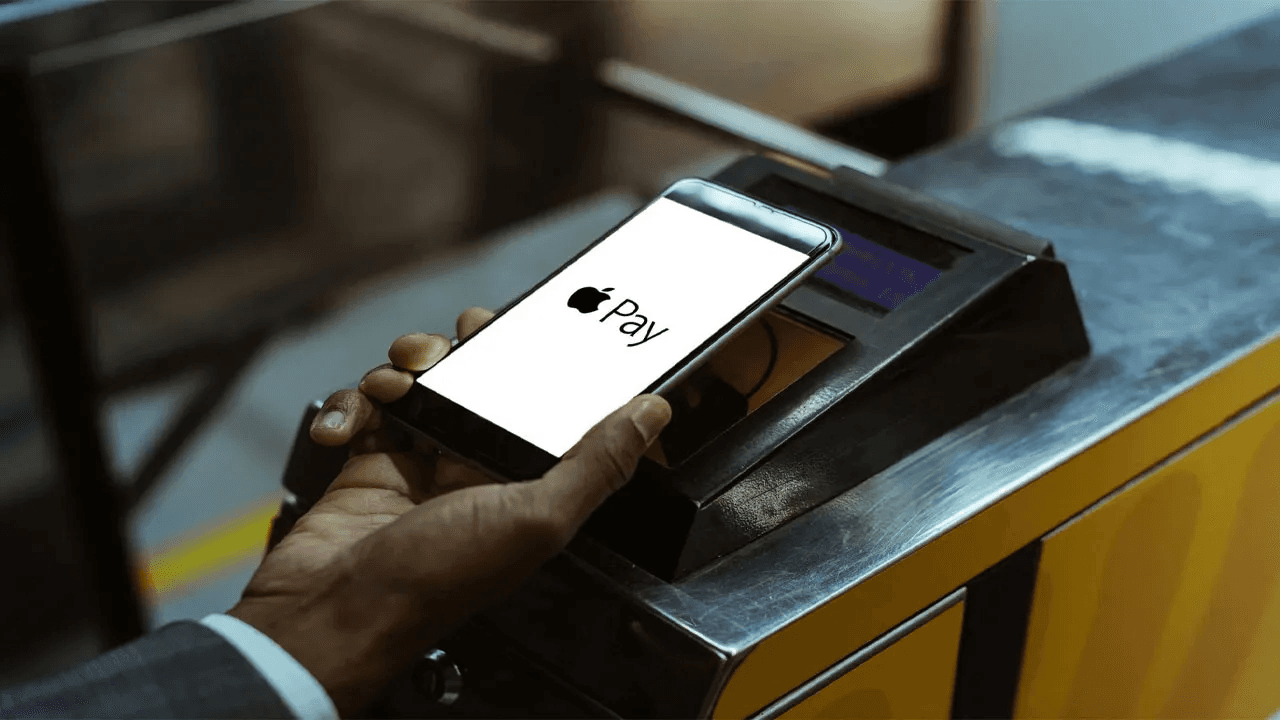
Contactless NFC payment on an iPhone opened to third-party apps by Apple

Payment Systems

Apple opens NFC payments to third-party apps

Under the EU Digital Markets Act, Apple will let third-party developers in the European Economic Area offer NFC contactless payments inside iOS apps without Apple Pay or Apple Wallet, opening the way for banks and payment services to launch their own tap-to-pay solutions.