Merchant & POS
What does Not Onus mean?
Not Onus is a payment systems term meaning "Not On Us": a situation where the card-issuing bank and the POS/ATM (acquiring) bank differ. Such transactions are settled through clearing between the two banks.
Search
74 articles found
Merchant & POS
Not Onus is a payment systems term meaning "Not On Us": a situation where the card-issuing bank and the POS/ATM (acquiring) bank differ. Such transactions are settled through clearing between the two banks.
Payment Systems
The BRSA has published a draft regulation amending the Regulation on Debit Cards and Credit Cards. It introduces the card scheme definition, a customer right to choose the card scheme, and an obligation for acquirers to define licensed schemes on merchant POS devices.

Merchant & POS
Visa's Merchant Data Standards Manual covers classification, identification and data standard requirements for merchants, payment facilitators and marketplaces, including merchant naming, location and MCC rules. Here is what it contains and where to find it.
Merchant & POS
Since the MCC code is a merchant's category code, it's critical for the checks performed during merchant onboarding and authorization, including campaigns and restrictions.
Merchant & POS
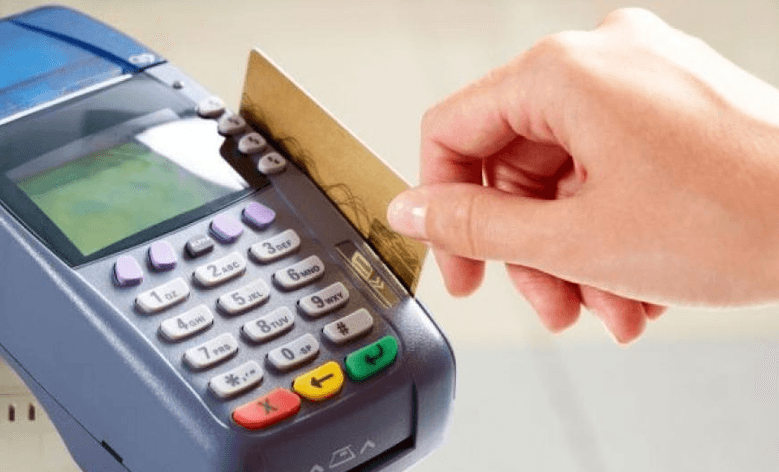
When a chip can't be read due to a chip fault or the card being inserted incorrectly, the transaction is completed by swiping the magnetic stripe on the right side of the POS. Can chipless cards do fallback?
Payment Systems
Message 200 is generated for transactions initiated from POS applications, and the acquiring bank responds with message 210. Learn how 100/110 messages route approvals via the issuing bank, and common rejection reasons.
Merchant & POS
Banks check merchants against a termination list before issuing a POS device. Learn the main reasons, such as counterfeit card acceptance, excessive chargebacks, and fraud, that can lead a bank to terminate a merchant agreement.
Payment Systems
Although many important terms are used in payment systems, the expressions below are its cornerstones — the ABCs of payment systems, so to speak. Issuer: the credit card company, usually a bank, that issues the card and tracks debt, credit, bonus points, and other services for the customer.

ISO 8583
F41 - CARD ACCEPTOR TERMINAL IDENTIFICATION: the terminal where a transaction took place. An 8-character alphanumeric value generated by the acquirer bank and assigned to the POS, managed as a unique terminal number at the acquirer.
Chargeback
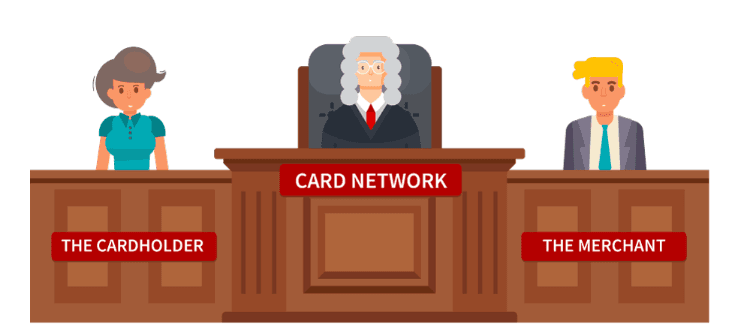
Arbitration, by definition, is a dispute resolution method in which disputes are settled by arbitrators the parties choose themselves, rather than by official courts. In payment systems, it follows a chargeback when the issuer and acquirer cannot agree.
Credit Card
In the standard authorization flow, the transaction is initiated by the acquirer (POS bank) and forwarded to the issuer (card-issuing institution). The process is completed once the issuer responds. However, this isn't always possible; when the issuer fails to respond, BKM steps in...
Merchant & POS
Pre-authorization closing turns a pre-authorized transaction into a financial one, posting it to the merchant and cardholder accounts. See how amounts and available limit are affected.