First, it is worth giving brief background on the credit card minimum payment amount. You can find detailed information on how the minimum payment amount is calculated in my post What is the minimum payment amount and how is it calculated?
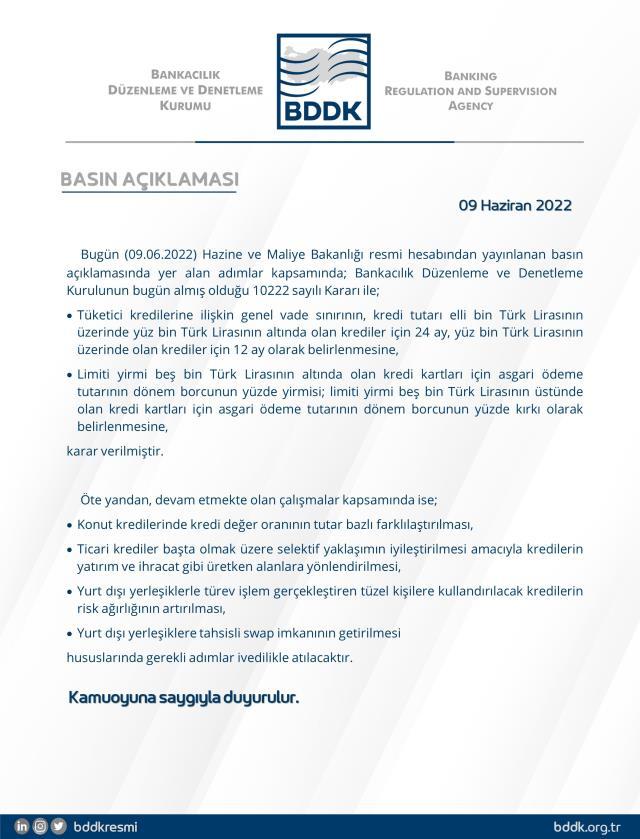
The BRSA periodically changes the method used to calculate the minimum payment amount. In its announcement dated 09.06.2022, the BRSA shared that a change had been made to the minimum payment calculation.
From now on, the card limit will be a key factor in calculating the minimum payment amount;
- For credit cards with a limit below 25,000 lira, the minimum payment amount was set at 20 percent of the period debt,
- For credit cards with a limit above 25,000 lira, the minimum payment amount was set at 40 percent of the period debt.
In this case, we can say that requests to banks to update card limits will increase for cards with a limit above 25,000 TL. The 25,000 TL threshold will be a very decisive factor in limit increase requests.
So what do banks need to do in this situation?
- First, they need to inform citizens about this change through social media as well as SMS/email.
- They should make a particular effort to reach cardholders whose card limits are in the 25,000-30,000 TL band; if necessary, customers should be called through customer services and given the necessary information.
- Customers who request a limit increase above 25,000 TL should be informed about the new regulation.
- Considering that the number of customers who cannot pay the minimum payment amount of their card debt may increase, monitoring actions in bank systems should be carried out more carefully.
So what will the effect of this regulation on the market be?
- It will prompt cardholders who use their cards by paying only the minimum payment amount to spend less.
- There will be a decrease in card spending amounts and transaction counts.
- Assuming that e-money companies have a business model based on commissions charged on transactions, the revenues of e-money institutions will decrease.
- It will cause a decrease in transaction volume in the market.
- The number of cardholders who cannot pay their card debt will increase.
- It will cause an increase in the number of customers who fall into delinquency because the minimum card debt was not paid.
- Customers whose cards become delinquent will not be able to use their cards and may be negatively affected financially.
Although the regulation aims to get cardholders to spend only what they can afford to pay, it also brings the disadvantages I mentioned above.
In short, although a credit card is a good payment instrument when spent correctly according to income, it is a payment instrument that needs to be used in a controlled way because of high limits and the extra interest paid on overdue amounts.
As a cardholder, my recommendation is to spend only what you can pay and to make an effort to pay the entire amount shown on the statement on time, which will prevent possible problems.
You can access the text of the relevant announcement published by the BRSA at the link below:



