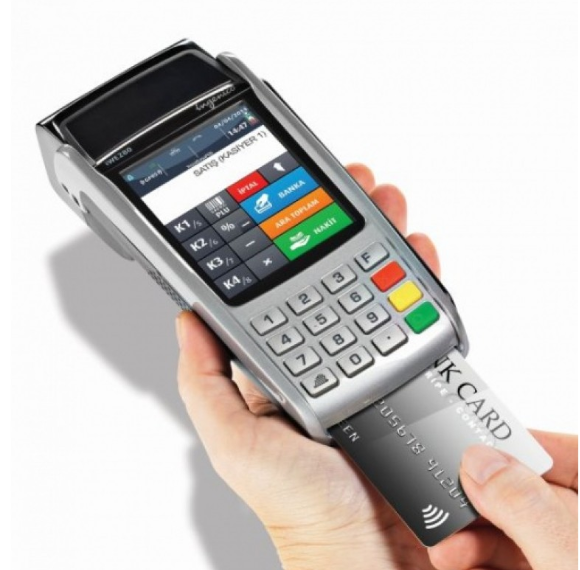
With the announcement published by the Revenue Administration (GIB) on 30/11/2023, a draft Tax Procedure Law General Communiqué has been prepared and published in order to complete the process of replacing old-generation payment recorder devices with new-generation payment recorder devices, to reduce cash use and to increase card payment options.
With the published draft communiqué, the subject of this Communiqué is the obligation for taxpayers required to use payment recorder devices to replace the old-generation payment recorder devices they use with new-generation payment recorder devices, and to enable debit card payments through new-generation payment recorder devices, in order to support the registered economy, expand card payment options and spread the use of new-generation payment recorder devices.
You can see the relevant articles of the communiqué below;
Obligation to migrate from existing EN OKCs to YN OKCs
ARTICLE 4–
- Pursuant to the General Communiqué on the Law Concerning the Obligation of Value Added Tax Taxpayers to Use Payment Recorder Devices, Series No. 69, published in the Official Gazette dated 11/4/2012 and numbered 28261, the Tax Procedure Law General Communiqué Serial No. 426, published in the Official Gazette dated 15/6/2013 and numbered 28678, and the Tax Procedure Law General Communiqué Serial No. 483, published in the Official Gazette dated 30/9/2017 and numbered 30196, first- and second-class merchants who sell goods, as is or after processing, to persons other than those who resell them, or who provide services to the same persons (making retail deliveries or performing services), must replace the EN OKCs (old-generation payment recorder devices) that they use to document sales of goods or services for which they are not required to issue an invoice under Law No. 213 with YN OKCs (new-generation payment recorder devices) by 2/9/2024, regardless of whether their fiscal memory is full. Taxpayers who wish may start using YN OKCs approved by the Ministry before this date as well.
- The YN OKCs purchased within the scope of the first paragraph must be put into use within 30 days following the invoice date, provided that this does not go beyond 2/9/2024, and within the same period the existing EN OKCs must also be scrapped in accordance with the principles set out in the General Communiqué on the Law Concerning the Obligation of Value Added Tax Taxpayers to Use Payment Recorder Devices, Series No. 60, published in the Official Gazette dated 15/5/2004 and numbered 25463.
- The service report, fiscal memory report and payment recorder device plate issued during the scrapping of existing EN OKCs may be delivered by hand to the relevant tax office by the taxpayer or the OKC authorized service, or may be sent by registered mail.
Obligation to use an active payment application for debit cards on YN OKCs
ARTICLE 5– (1) Among taxpayers within the scope of the obligation to use YN OKCs;
a) Those using EFT-POS-enabled YN OKCs;
- Those who have long used EFT-POS-enabled YN OKCs must, as of 3/6/2024, sign a merchant agreement with at least one bank or other institution or payment service provider and accept debit card payment requests through each YN OKC they use.
- Those who start using an EFT-POS-enabled YN OKC after 3/6/2024 (including that date) must, within 30 days at the latest from the activation date of the device, sign a merchant agreement with at least one bank or other institution or payment service provider and accept debit card payment requests.
- Those who start using an EFT-POS-enabled YN OKC between the publication date of the Communiqué and 3/6/2024 must, as of 3/6/2024, sign a merchant agreement with at least one bank or other institution or payment service provider and accept debit card payment requests through each YN OKC they use. However, if there is less than 30 days between the date the EFT-POS-enabled YN OKC started to be used and 3/6/2024, acceptance of debit card payment requests through each YN OKC must begin within 30 days.
b) Those using simple/computer-connected YN OKCs;
- Those who have long used simple/computer-connected YN OKCs must, as of 3/6/2024, sign a merchant agreement with at least one bank or other institution or payment service provider and, after connecting each YN OKC they use to an EFT-POS, accept debit card payment requests.
- Those who start using a simple/computer-connected YN OKC after 3/6/2024 (including that date) must, within 30 days at the latest from the activation date of the device, sign a merchant agreement with at least one bank or other institution or payment service provider and, after connecting the EFT-POS devices to the OKC, accept debit card payment requests.
- Those who start using a simple/computer-connected YN OKC between the publication date of the Communiqué and 3/6/2024 must, as of 3/6/2024, sign a merchant agreement with at least one bank or other institution or payment service provider and accept debit card payment requests through each YN OKC they use. However, if there is less than 30 days between the date the simple/computer-connected YN OKC started to be used and 3/6/2024, acceptance of debit card payment requests through each YN OKC must begin within 30 days.
Other matters
ARTICLE 6–
- Within the obligations introduced by Article 5 of this Communiqué, EFT-POS-enabled YN OKCs on which no applications accepting debit card payment requests under a merchant agreement have been installed within the periods set out in that article, and simple/computer-connected YN OKCs that have not been connected to an EFT-POS, will be closed to use and made passive within 15 days following the end of these periods. Once the said obligations are fulfilled, the YN OKCs will be reopened for use.
- YN OKCs on which debit card payment requests are not accepted because no merchant agreement was made with at least one bank or other institution or payment service provider within 15 days following the date on which the merchant agreements made within the scope of the obligations introduced by Article 5 of this Communiqué ended (where there is no longer any option to pay with debit cards) will be closed to use and made passive. Once the said obligations are fulfilled, the YN OKCs will be reopened for use.
- The provisions of the General Communiqué on the Law Concerning the Obligation of Value Added Tax Taxpayers to Use Payment Recorder Devices, Series No. 69, the Tax Procedure Law General Communiqué Serial No. 426, the Tax Procedure Law General Communiqué Serial No. 483 and other related communiqués that are not contrary to this Communiqué continue to apply.
- The Administration is authorized to determine, through technical guides to be published at ynokc.gib.gov.tr, the information to be obtained electronically from YN OKCs within the scope of this Communiqué, the time of transfer of the information to the GIB Technology systems (instant and/or periodic), the transfer method (directly or via OKC TSMs) and other procedures and principles concerning the transfer, as well as the actions to be taken for devices found not to have fulfilled the obligations set out in Article 5 of this Communiqué.
- The Administration is authorized to extend the periods set out in this Communiqué, separately or together, by tax and taxpayer type, taxpayer groups, sector, fields of activity, number of payment recorder devices, business or production volume, and provincial and district boundaries, by announcing this at ynokc.gib.gov.tr.
Penal sanctions
ARTICLE 7–
- The relevant penalty provisions of Law No. 213 and Law No. 3100 apply to taxpayers who do not fulfill the obligations stipulated within the periods set out in this Communiqué.
Under the GIB draft regulation;
1- Those using new-generation OKCs must sign a merchant agreement with at least one payment service provider as of “3/6/2024”, and
2- The process of replacing old-generation OKCs with YN OKCs will be completed by “2/9/2024”.
You can access the relevant draft communiqué at the link below:



