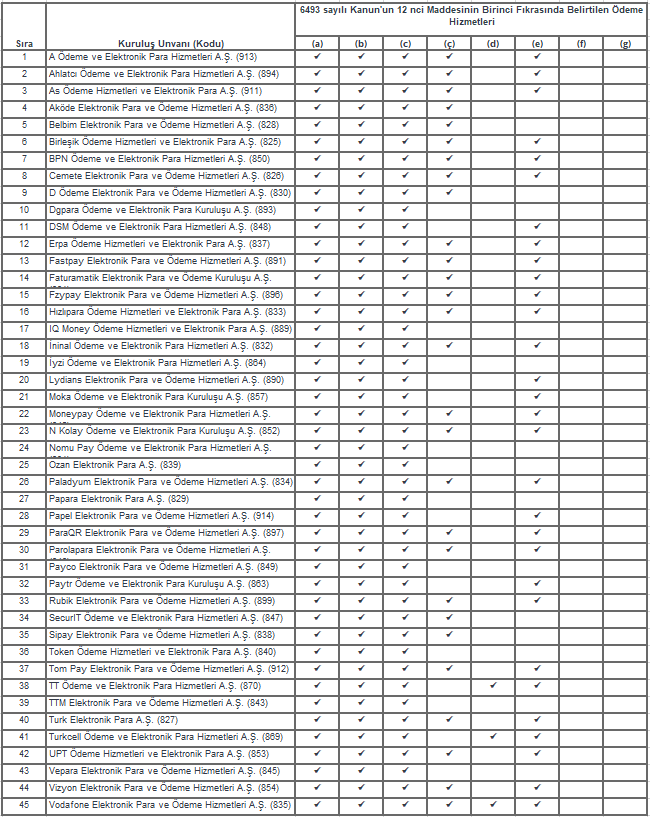
All e-money institutions are authorized to issue e-money under Article 18, paragraph 2 of Law No. 6493. In addition, the payment services they are authorized to provide under Article 12 of Law No. 6493 are shown in the table below.
Article 12 of the Law is as follows:
ARTICLE 12 – (1) Under this Law, payment services means;
a) All operations required for operating a payment account, including services that enable depositing money into and withdrawing money from a payment account,
b) Money transfers, including direct debit (also one-off direct debit), payment transactions made with a payment card or a similar instrument, and standing payment orders, which involve the transfer of funds in the payment account that a payment service user holds with a payment service provider,
c) Issuing or acquiring of payment instruments,
d) Money remittance,
e) Payment transactions where the sender's consent to the payment transaction is given through an information technology or electronic communication device and the payment is made to an information technology or electronic communication operator acting only as an intermediary between the payment service user and the supplier of goods or services,
f) (Added: 12/11/2019-7192/8 art.) Payment initiation services provided, at the request of the payment service user, with respect to a payment account held with another payment service provider,
g) (Added: 12/11/2019-7192/8 art.) Services of providing consolidated information on online platforms about one or more payment accounts held by the payment service user with payment service providers, provided that the consent of the payment service user is obtained,
h) (Added: 12/11/2019-7192/8 art.) Other transactions and services in the field of payments that reach a level of total size or scope of impact to be determined by the Bank,
refers to.
Table – E-Money Institutions in Operation and the Scope of Their Operating Licenses