Payment Initiation Service Providers – PISP (Payment Initiation Service Provider): what is it?
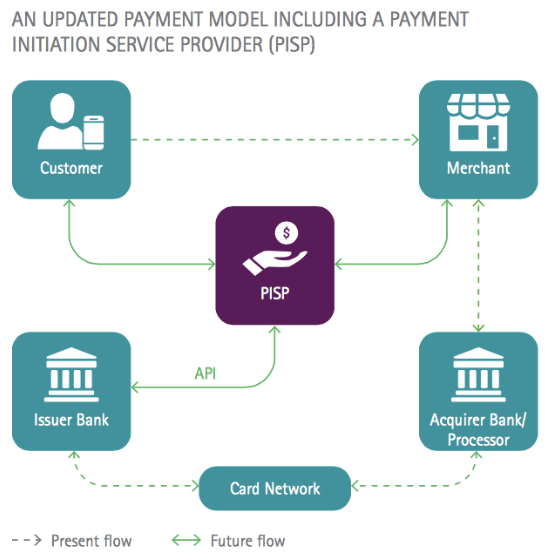
A Payment Initiation Service Provider is a service provider that can initiate a payment transaction on behalf of a customer; in other words, with the customer's consent, it can withdraw money directly from the customer's account. If the customer has more than one account, which account the money will be deducted from can be selected.
In the future, it is clear that more Payment Initiation Service Providers will be on the market. The most widely used Payment Initiation Service Provider in the world is Vipps (a payment app) in Norway. Experts believe that apps such as Facebook will also enter this system in the future.
So what are the advantages of using a Payment Initiation Service Provider?
- Using a Payment Initiation Service Provider offers every customer many advantages. First, you no longer need to access your online bank account to pay bills.
- The Payment Initiation Service Provider holds all of your banking information and pays all bills related to the customer's activity from the selected customer account.
- Another benefit of using a Payment Initiation Service Provider is that you can use it to pay for products and services at any physical store, app, or web store that has an agreement with your preferred Payment Initiation Service Provider.
- Since Payment Initiation Service Providers are not tied to a single bank, they are free to make agreements that benefit all customers, not just one bank's customer base.
In the future, as a result of the European PSD2 directive, customers will also be able to use their preferred Payment Initiation Service Provider while traveling in different European countries.



