Skip to content

Search

"reason codes"

88 articles found

Diagram illustrating card fraud and forgery in card payments

Security

What Is Forgery in Card Payments?

Forgery in card payments means transactions made with card details without the cardholder's knowledge, or purchases with counterfeit or stolen cards. Merchants cannot eliminate fraud and chargeback risk, but they should aim to reduce it to reasonable levels.

Diagram illustrating the structure of ISO 8583 field F43

ISO 8583

ISO 8583 Field Descriptions (F43)

F43 - CARD ACCEPTOR NAME AND LOCATION: the field that holds the name and location of the merchant/ATM where a card transaction took place. It is 40 characters long and alphanumeric.

Illustration explaining how a card's CVV value is generated

Credit Card

How is CVV generated?

CVV is a very critical 3-digit value used during a card's authorization process. The CVV value is encoded in the card's magnetic stripe data (Track 1 and Track 2). Is it generated by an algorithm or chosen at random?

POS terminal used for a card payment transaction

Merchant & POS

What Is a Timeout in Payment Systems?

In the world of payment systems, both the issuer (the cardholder's bank) and the acquirer (the POS/ATM bank) must follow certain rules for card transactions made through a POS terminal or an ATM. Responding to transactions within a certain time is one of these rules.

Physical credit card compared with a virtual card on a mobile phone

Credit Card

Physical or Virtual Credit Card: Which Do You Prefer?

Digitalization is reshaping payment systems. Credit cards are moving from physical plastic to virtual cards, e-wallets and mobile payments. Will physical card use disappear completely? Here is a look at the trends, Generation Z and the remaining gaps.

Example of a combo card showing credit card information on the front and debit card information on the back

Credit Card

What is a combo card?

A combo card is a next-generation card that combines both a credit card and a debit card on a single card. Although designs vary visually, the front typically carries the credit card information and the back the debit card information.

Illustration representing payment instruments such as cards and mobile devices

Payment Institutions & E-Money

What is a payment instrument?

Law No. 6493 on Payment and Securities Settlement Systems, Payment Services and Electronic Money Institutions defines a payment instrument as a personalized device such as a card, mobile phone, or password.

Diagram explaining the MCC merchant category code field in ISO 8583 messages

ISO 8583

ISO 8583 Field Descriptions (F18)

F18-MERCHANT TYPE: This is the merchant's category code (MCC) information. It must contain values from the Mastercard or Visa MCC Code list. It is a 4-digit numeric value. For ATM transactions, MCC code 6011 should be sent. The role of MCC in authorization...

Illustration of a smartphone used as a mobile POS payment terminal

Merchant & POS

Are POS Terminals Becoming Obsolete?

Today, as credit cards shift from physical to virtual use, a similar move has come from the POS side. We have begun to see mobile phones used as POS devices becoming a serious rival to physical POS terminals.

Embossed debit card with raised card number and cardholder name

Debit Card

What is an embossed debit card?

The main difference between embossed debit cards and standard debit cards is that the card number, cardholder name, and expiration date are printed in raised, embossed format rather than flat.

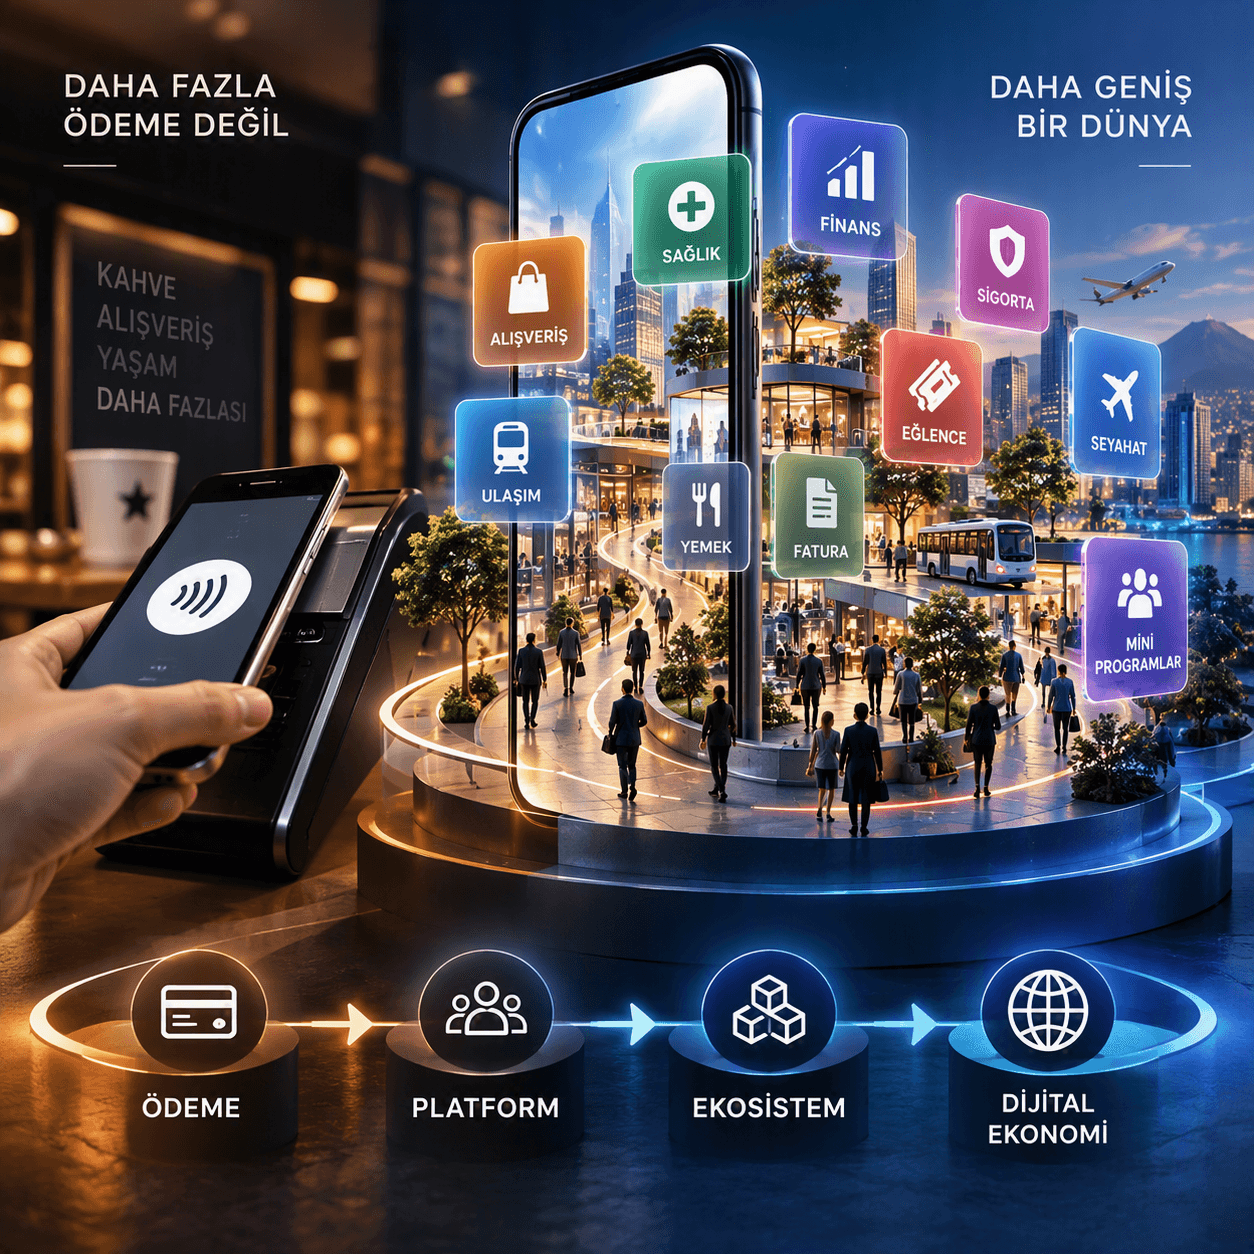
Illustration of a closed-loop payment ecosystem growing through loyalty, data, and new services

Closed-Loop Payments

Why Do Closed-Loop Payment Systems Want to Grow? | Series #6

Why does a coffee chain build its own loyalty program, and why does a payment app keep adding services? This post looks at how loyalty, data, and new services drive the growth of closed-loop payment systems, and at the financial layers behind that growth.